Europe may welcome nearly half of the world’s international travellers, but maintaining that global pre-eminence will require decisive structural overhauls across border facilitation, private-sector capital access, and long-haul source markets.
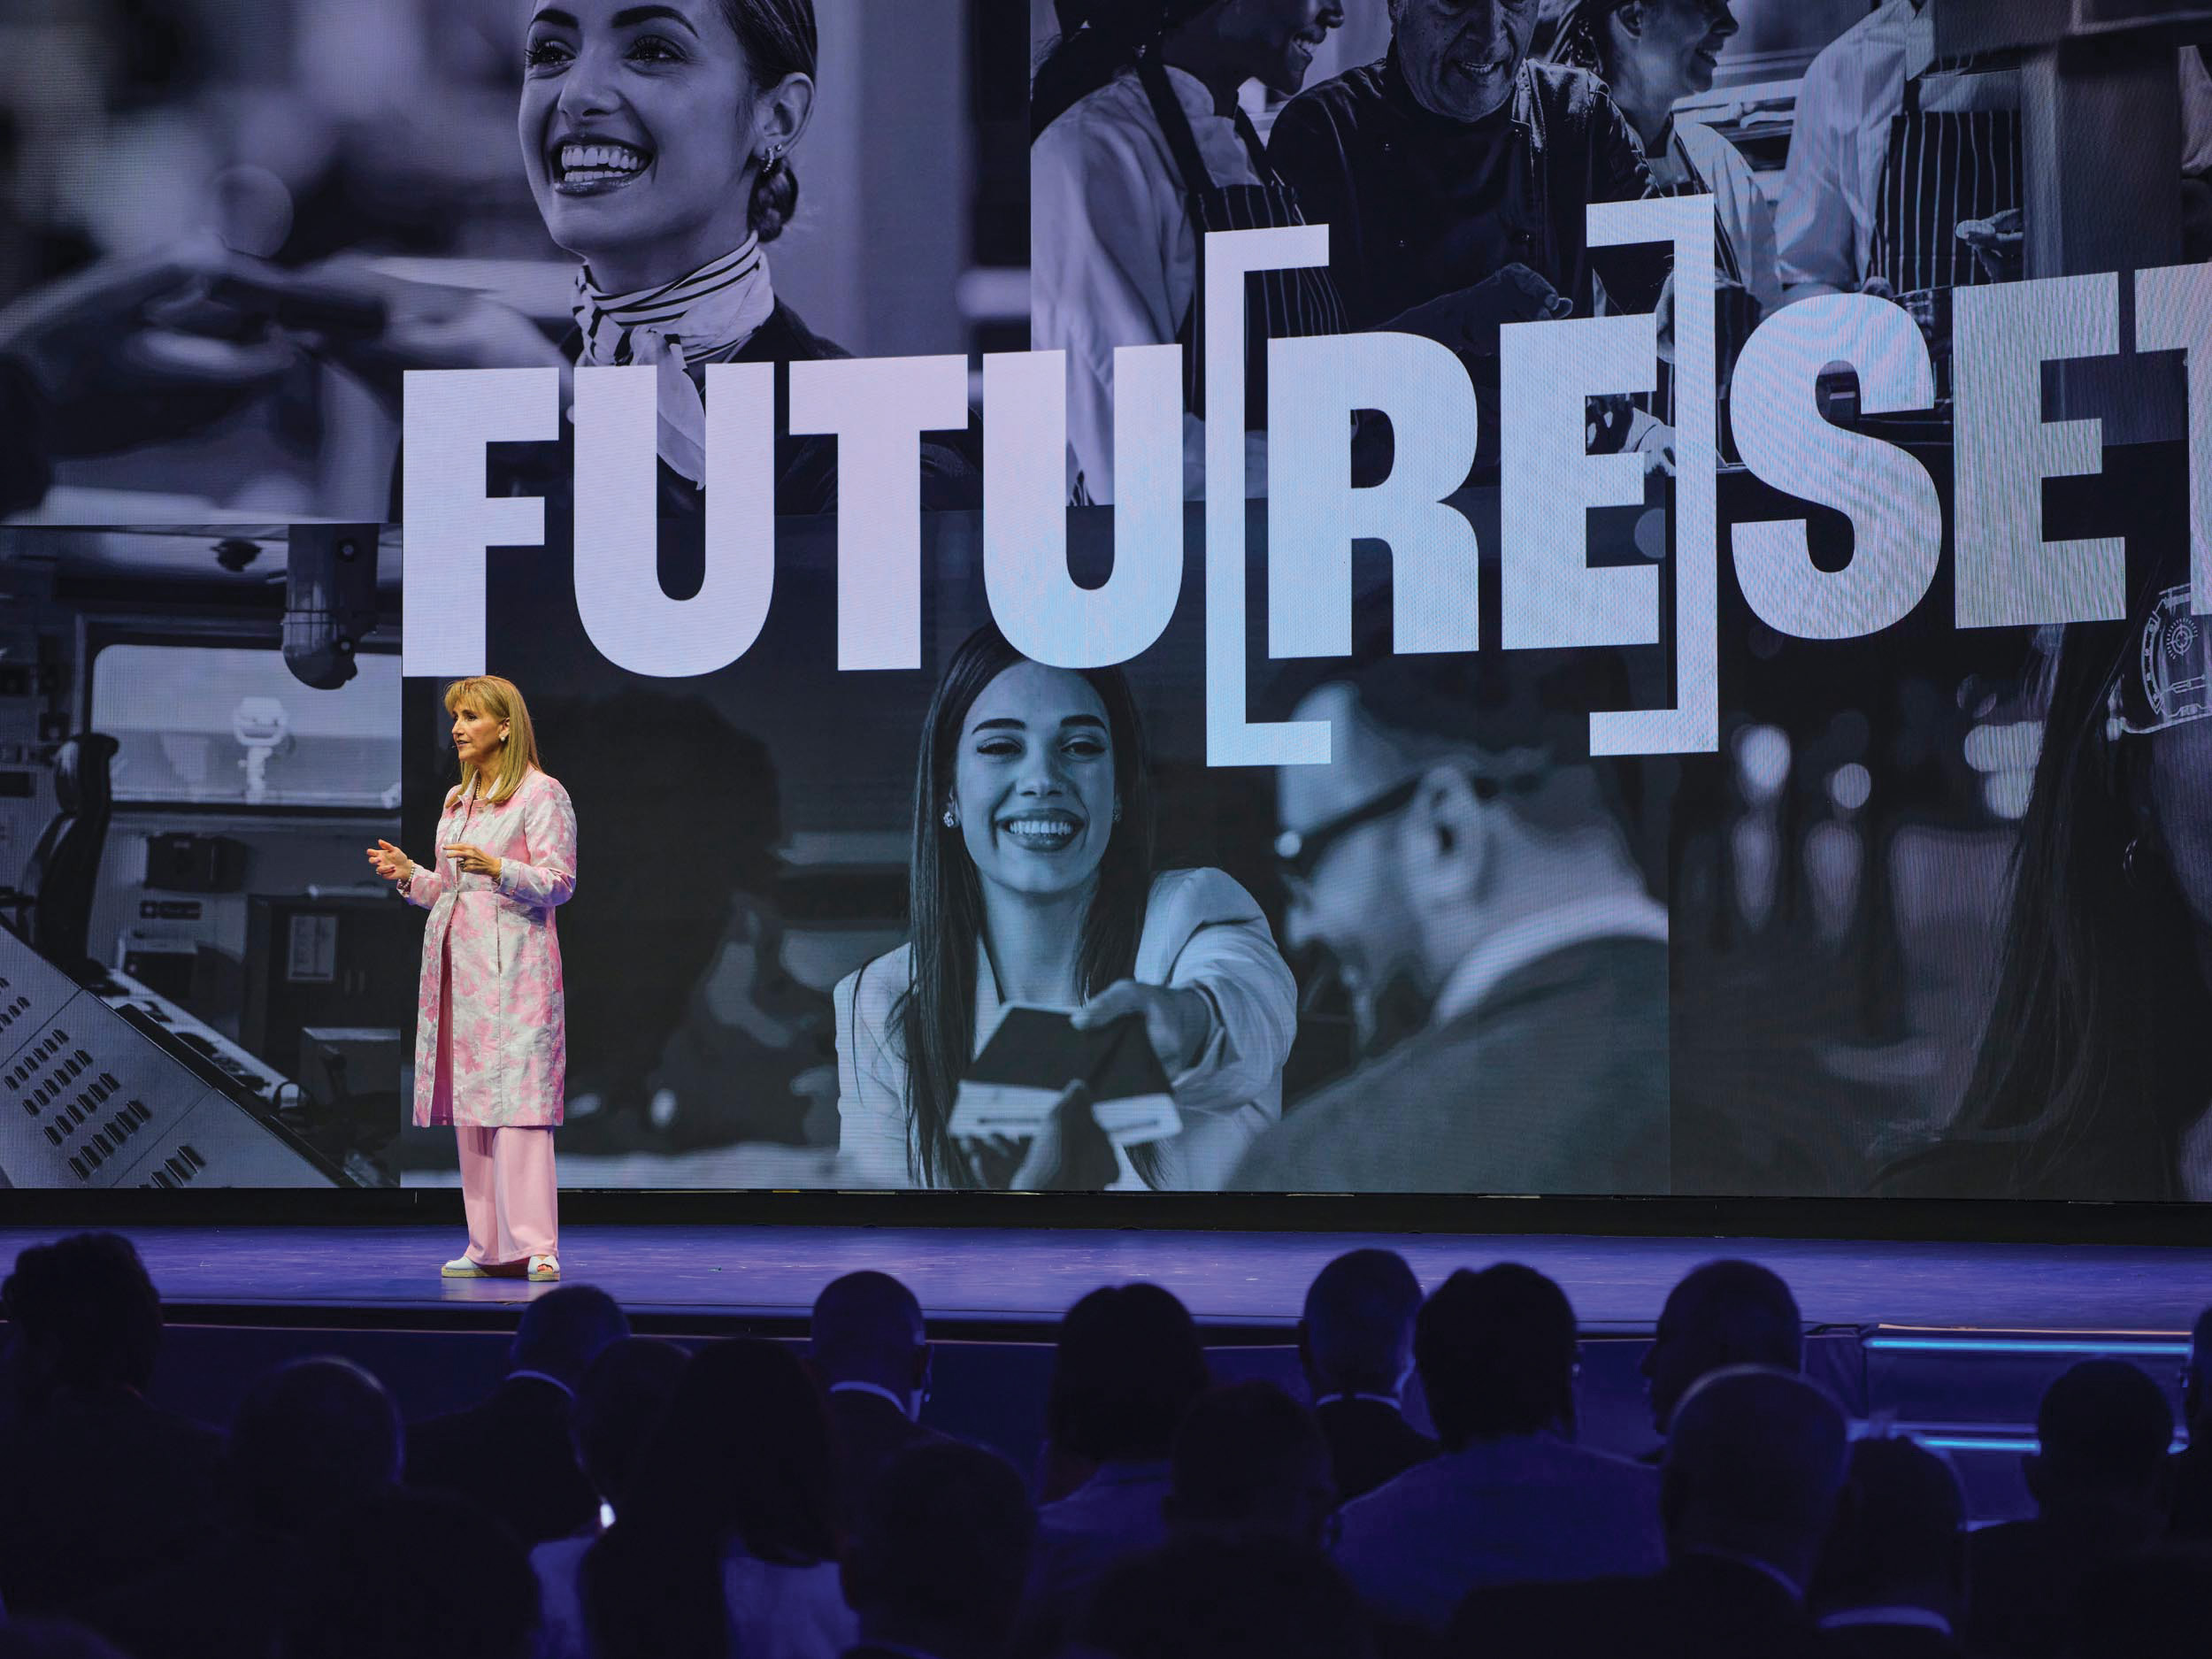
Unveiled during the 26th WTTC Global Summit in Valletta, the World Travel & Tourism Council’s strategic report, titled Travel & Tourism in Europe: A Deep Dive Into Growth, Outlook and Policy, details eight core priorities designed to help regional governments capture a larger share of the next decade of travel expansion.
The findings arrive at a critical policy crossroads. As European countries roll out refreshed national masterplans, the European Commission prepares its first dedicated EU Tourism Strategy, and negotiations continue over the European Union's 2028–2034 Multiannual Financial Framework, private-sector leaders have a rare opening to position travel and hospitality as a recognised strategic ecosystem rather than an auxiliary economic driver.
In 2025, the sector generated nearly $3 trillion for Europe’s economy, accounting for 9.4% of total regional gross domestic product and sustaining 40.7 million jobs. Non-EU countries generated more than a quarter of that total at $834 billion, led by the United Kingdom as Europe’s second-largest travel economy. Over the immediate term, travel and tourism is projected to expand by 3.1% in 2026, significantly outpacing the 1.1% growth rate forecast for the broader European economy, before climbing toward $3.8 trillion and over 50 million jobs by 2036.
While Europe recorded 757.3 million international overnight arrivals in 2025 and captured $835 billion in visitor spend, the regional travel trade balance reveals a concerning underlying imbalance.
Nearly three-quarters of all inbound arrivals to Europe originated from within Europe itself. When intra-regional journeys are excluded, Europe shifts from a headline $33.9 billion travel trade surplus to an estimated $45 billion deficit. In practical terms, European residents are spending far more on journeys beyond the region than incoming long-haul visitors are spending across European destinations.
Recovery across premium inbound feeder markets also remains uneven. Inbound arrivals from the Asia-Pacific region sat 4.8% below 2019 levels in 2025, with China trailing pre-pandemic volumes by 43.2% and key markets like Japan and South Korea remaining roughly 30% behind historical highs. To correct this imbalance, WTTC recommends establishing dedicated public-private marketing alliances across major overseas hubs, shifting key performance indicators from headline arrival volumes to net-yield market mixes, and pairing guaranteed promotion budgets with simplified border access.
Entry friction remains one of the sharpest competitive bottlenecks facing Europe's long-haul appeal. Schengen member states issued 5.3 million multiple-entry visas in 2025, marking a 40% decline compared to 2019 benchmarks and reducing multiple-entry issuances from 59% down to 51.7% of all processed visas.
To overcome these structural hurdles, the council is urging regional authorities to accelerate the deployment of the digital Schengen visa, re-establish predictable multi-year visa issuances for regular commercial and leisure travellers, launch an EU-wide trusted traveller scheme reciprocal with global systems like US Global Entry, and finalise a unified, workable biometrics architecture across European airport hubs.
Capital investment into Europe's travel and tourism sector reached $259 billion in 2025. While representing a 7.1% year-on-year rise, regional capital deployment remains 3.6% below 2019 levels, trailing investment velocity seen across Asia-Pacific and North America. WTTC is calling on policymakers to formally designate travel and tourism as a strategic ecosystem within the upcoming multi-year financial framework, unlocking dedicated financing instruments for operators and independent enterprises.
Simultaneously, environmental adaptation has emerged as an urgent operational priority. While emissions intensity dropped 14.8% between 2019 and 2024, the sector still generates 6.3% of Europe’s total greenhouse gas emissions. Mediterranean destinations, which capture 52.2% of Europe's inbound spending, face acute vulnerability to intense heatwaves and water stress, necessitating ring-fenced capital for localised nature protection, municipal water systems, and the rapid adoption of sustainable aviation and maritime fuels.
With international arrivals to Europe forecast to hit 1.14 billion by 2036, long-term stability hinges on labour capacity and modern technological integration.
The sector continues to lead in youth employment, yet demand for qualified personnel is rapidly outstripping supply. Germany and Greece are projected to face acute labor shortfalls of 26% and 27% respectively by 2035, underscoring the urgent need for cross-border apprenticeships and standard recognition for the Hospitality and Tourism Skills Passport.
To prevent community fatigue and infrastructure strain, municipal authorities are being advised to abandon crude volume metrics in favour of value-driven stewardship, utilising predictive data platforms to spread traveller traffic across secondary destinations and shoulder seasons while ensuring visitor levies are legally ring-fenced for destination management. At the enterprise level, targeted digital grants and proportionate regulatory rules will be vital in helping small businesses harness artificial intelligence, alongside integrated multimodal ticketing systems that merge rail, air, and road connections across regional frontiers.